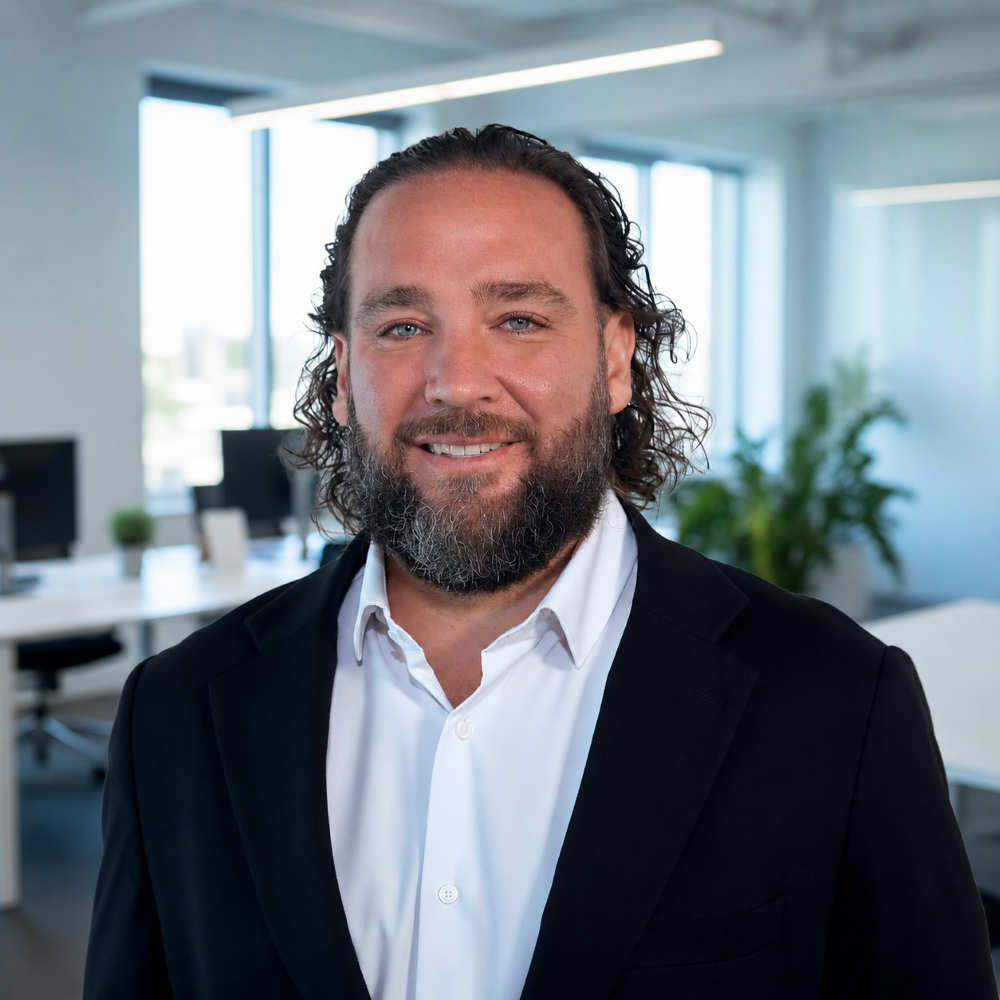
When financial pressure becomes a financial crisis, most people don’t know where to turn or wait too long to ask for help. Chad Van Horn, Esq., founding partner of Van Horn Law Group, P.A., has spent his career helping South Floridians understand their options before the situation becomes dire. Van Horn breaks down the realities of debt, the alternatives to bankruptcy, and why the smartest move someone can make is getting informed early.
SFBW: What are the most common alternatives to bankruptcy, and when does each one make the most sense?
Chad Van Horn: The most common alternatives are debt negotiation, debt management plans, consolidation, mortgage modification, forbearance, and sometimes simply creating a structured repayment plan.
SFBW: Debt negotiation can make sense when someone has lump-sum funds available or can save toward settlements, and the debt is mostly unsecured, like credit cards or personal loans.
CVH: Debt management through a reputable credit counseling agency can work when the person has steady income and needs lower interest rates or a more organized payment structure.
Consolidation can be helpful, but only if it actually lowers the cost of the debt and does not just move the problem around.
For homeowners, loan modification or loss mitigation may be a better first option than bankruptcy if the goal is to save the home and the lender is willing to work with them.
SFBW: A lot of people wait until they’re in crisis to seek legal help. At what point in the debt spiral should someone actually speak to an attorney, even if they hope to avoid filing?
CVH: Sooner than most people think. You do not need to wait until you are being sued, garnished, or facing foreclosure to speak with an attorney. In fact, waiting that long often limits your options. I think someone should get advice when they are consistently unable to make more than minimum payments, borrowing from one source to pay another, falling behind on secured debts, receiving collection letters, or feeling like there is no realistic path to catch up.
SFBW: Medical debt and student loans are two of the biggest drivers of financial distress. Are there specific strategies you’ve seen work for each that don’t involve filing?
CVH: For medical debt, the first step is to verify the bill. Ask for an itemized statement, compare it to the explanation of benefits, look for duplicate charges or coding issues, and ask whether the hospital has a charity care or financial assistance policy. Many people do not realize they may qualify for a reduction even if they are working or have insurance. You can also ask for an interest-free payment plan or negotiate a reduced balance, especially if the account has not gone to collections yet.
Federal student loans may have income-driven repayment options, deferment or forbearance in limited situations, forgiveness programs, and Public Service Loan Forgiveness for certain government or nonprofit employees. Private student loans are usually tougher, but there may still be options to negotiate, refinance, or defend a lawsuit if one is filed.
The mistake people make with both medical debt and student loans is avoidance. These are complicated debts but ignoring them almost always makes the situation worse.
SFBW: What are the warning signs that someone is heading toward a financial cliff, and what are some immediate steps they should take to try to course-correct?
CVH: The big warning signs are using credit cards for basic living expenses, making only minimum payments, taking payday loans or cash advances, falling behind on mortgage or car payments, ignoring collection letters, getting sued, or draining retirement accounts to keep up with debt.
The immediate step is to stop guessing. Build a simple financial snapshot: income, necessary expenses, total debt, interest rates, arrears, and any pending lawsuits or deadlines. Then prioritize. The goal is not always bankruptcy. The goal is stability. Sometimes that means negotiating, sometimes it means restructuring, and sometimes bankruptcy is the tool that gives someone the fresh start they need. The important thing is to face the problem early enough that you still have choices.