With rising housing costs, insurance premiums, and everyday expenses putting pressure on South Florida households, making informed financial decisions has become increasingly important. Whether purchasing a home, applying for a business loan, or simply trying to build savings, understanding how to manage money and credit can make a significant difference.
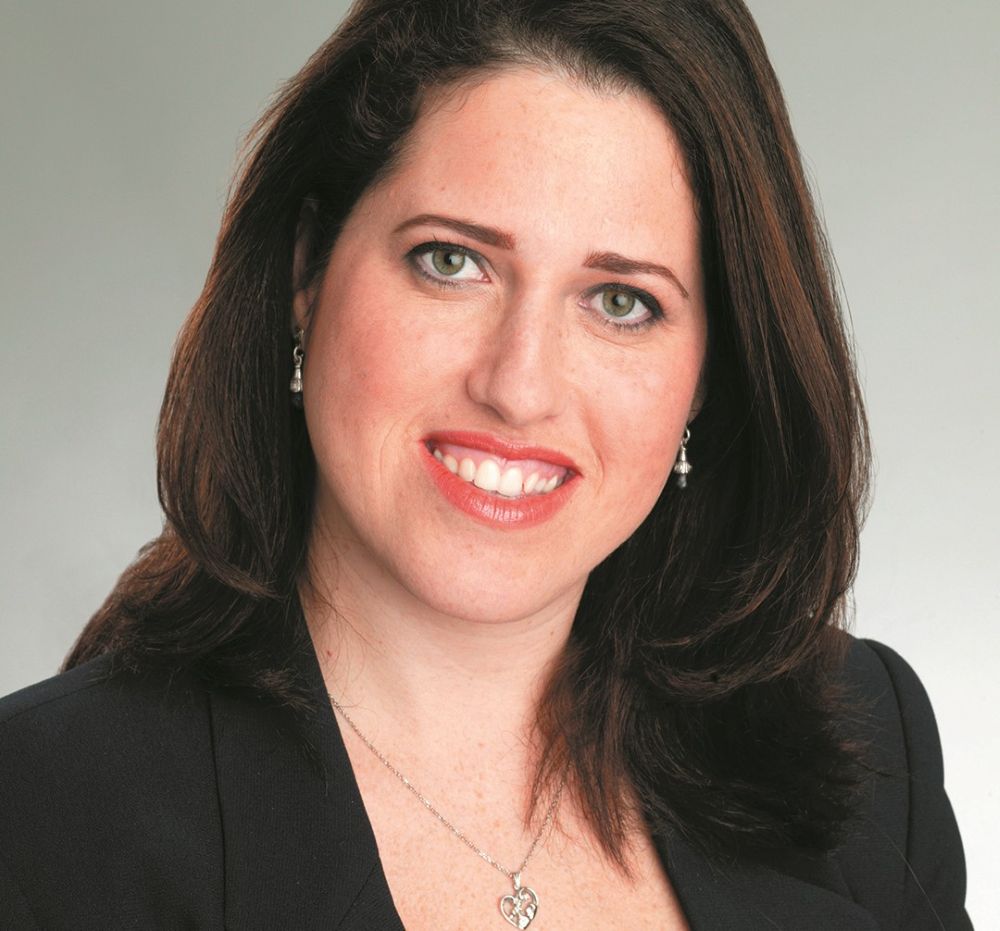
Biana Murnane, president and CEO of Broward-based BrightStar Credit Union, has spent nearly three decades with the financial institution, which serves more than 61,000 members and manages nearly $1 billion in assets. As one of the few women leading a major South Florida credit union, Murnane has made financial education and helping members achieve financial stability important parts of her leadership.
SFBW spoke with Murnane about the most common credit mistakes, what lenders look for when evaluating loan applications, and the financial lessons everyone should learn before entering adulthood.
SFBW: What should someone do before applying for a home, auto, or business loan to improve their chances of approval and secure a favorable interest rate?
Bianca Murnane: Before applying for a loan, it’s important to take a close look at your overall financial picture. Start by reviewing your credit report for any errors and understand your credit score, since credit history can play a significant role in both loan approval and the interest rate you may receive. Paying down existing debt, particularly high credit card balances, can also help strengthen your application and improve your debt-to-income ratio.
Consumers should also make sure they can demonstrate stable income and have savings set aside. Depending on the type of loan, lenders may look at employment history, income, existing financial obligations, and the amount of money available for a down payment or unexpected expenses. In the months leading up to an application, avoid making large purchases on credit or opening new credit accounts, as those actions can affect your credit profile.
Most importantly, do your homework before signing anything. Compare rates, terms, fees, and monthly payments, and don’t be afraid to ask questions. A loan should not only be something you can qualify for; it should comfortably fit within your budget and support your broader financial goals. Working with a trusted financial institution early in the process can also help you understand your options and identify steps you can take to put yourself in the strongest position before applying.
SFBW: What are the most common credit mistakes, and what three steps can someone take right now to improve their credit score?
BM: Some of the most common credit mistakes are also the most avoidable: making late payments, carrying high credit card balances, and not regularly reviewing your credit report. People can also hurt their credit by applying for too many new accounts within a short period of time or using too much of their available credit, even if they are making the minimum payments each month.
If you want to start improving your credit today, focus on three things:
Pay every bill on time: Payment history is an important factor in your credit score, so setting up automatic payments or reminders can help ensure you never miss a due date.
Work on reducing credit card balances: Paying down revolving debt can lower your credit utilization and demonstrate responsible credit management.
Review your credit report for errors. Check your reports regularly to make sure the information is accurate and dispute any errors you find.
Improving your credit doesn’t happen overnight, but small, consistent financial habits can make a meaningful difference over time.
SFBW: With South Florida’s high cost of living, what strategies do you recommend for building savings, managing debt, and creating greater financial security?
BM: With the cost of housing, groceries, insurance, and other everyday expenses continuing to put pressure on South Florida families, building financial security can feel challenging. The first step is to create a realistic budget based on what you are actually spending today. Review your monthly expenses, identify areas where you can cut back, and prioritize the essentials before discretionary spending.
Building an emergency fund should also be a priority, even if you can only start with a small amount. Setting up an automatic transfer into savings each payday can make saving more manageable and help turn it into a habit. Over time, those smaller contributions can create an important financial cushion for unexpected expenses, such as a car repair, medical bill, or home expense, without having to rely on credit.
When it comes to debt, focus on developing a repayment strategy, particularly for high-interest debt such as credit card balances. Paying more than the minimum whenever possible can help reduce both the balance and the amount of interest you pay over time.
Most importantly, don’t underestimate the impact of small, consistent changes. Financial security isn’t necessarily about making dramatic changes overnight. It’s about developing sustainable habits, regularly reviewing your finances, and making intentional decisions that gradually put you in a stronger financial position.
SFBW: What do lenders consider beyond a credit score, and what should someone do if their loan application is denied?
BM: A credit score is important, but it’s only one part of the picture. Lenders typically look at several factors to understand a borrower’s overall financial health and ability to repay a loan. That can include income and employment history, existing monthly debt obligations, debt-to-income ratio, savings, and the amount being borrowed. Depending on the type of loan, lenders may also consider factors such as the size of a down payment or collateral.
If you are turned down for financing, don’t get discouraged. Start by understanding why your application was denied. The lender should be able to provide information about the factors that influenced the decision, which can help you identify what needs improvement. From there, you can focus on specific areas, whether that means paying down debt, building savings, correcting an issue on your credit report, or establishing a more consistent payment history.
I also encourage consumers to speak with their financial institution before immediately applying elsewhere. A banker or credit union representative can help you better understand your financial position, discuss other options that may be available, and create a plan for becoming a stronger borrower. A denial today doesn’t mean a denial forever. With the right information and a little time, you can strengthen your financial profile and be better positioned when you’re ready to apply again.
SFBW: What financial resources do consumers often overlook, particularly at credit unions, that could help them build long-term wealth?
BM: Many consumers overlook the financial education, personalized guidance, competitive loan rates, and lower fees often available through credit unions. These resources can help individuals make informed financial decisions, reduce borrowing costs, increase savings, and stay focused on long-term wealth-building goals.
One of the biggest opportunities consumers often overlook is taking advantage of the full range of resources their financial institution offers beyond basic checking and savings accounts. Credit unions, in particular, are member-focused institutions where you can get financial education, personalized guidance, competitive rates on loans and credit products, and lower or fewer fees. Those savings can make a meaningful difference over time.
Paying less interest on an auto loan or mortgage, reducing banking fees, and earning more on savings are all opportunities to redirect money toward larger financial goals, whether that’s building an emergency fund, buying a home, investing for retirement, or starting a business.
Consumers should also take advantage of financial education and one-on-one guidance. You don’t have to wait until you’re applying for a loan or facing a financial challenge to have those conversations.
Ultimately, building long-term wealth is often about maximizing the resources already available to you. Small savings, better borrowing decisions, and consistent financial planning can compound over time and help create a stronger financial future.
SFBW: How early should schools begin teaching financial literacy, and what money-management skills should every student have before graduating?
BM: Financial literacy is one of the most important life skills we can teach young people because nearly every student will eventually have to make decisions about earning, spending, borrowing, and saving money. At BrightStar, financial education is a major part of how we support our communities, and I believe those conversations should begin early.
In elementary school, children can start with basic concepts such as the difference between wants and needs, saving for a goal, and understanding that money is earned and choices have to be made about how it is spent. As students get older, those lessons should evolve to include budgeting, banking, credit, debt, investing, and understanding how interest works.
Before graduating from high school, every student should know how to create and manage a budget, open and responsibly use a bank account, build and protect their credit, understand a credit score, read a paycheck, and recognize the true cost of borrowing. They should also understand the importance of saving for emergencies and long-term goals, as well as the basics of investing and how starting early can benefit them over time.
We prepare students for college and careers, but we also need to prepare them for the financial decisions that come with adulthood. Giving young people that foundation before they earn their first full-time paycheck or apply for their first credit card can help them avoid costly mistakes and put them on a path toward greater financial independence and long-term security.