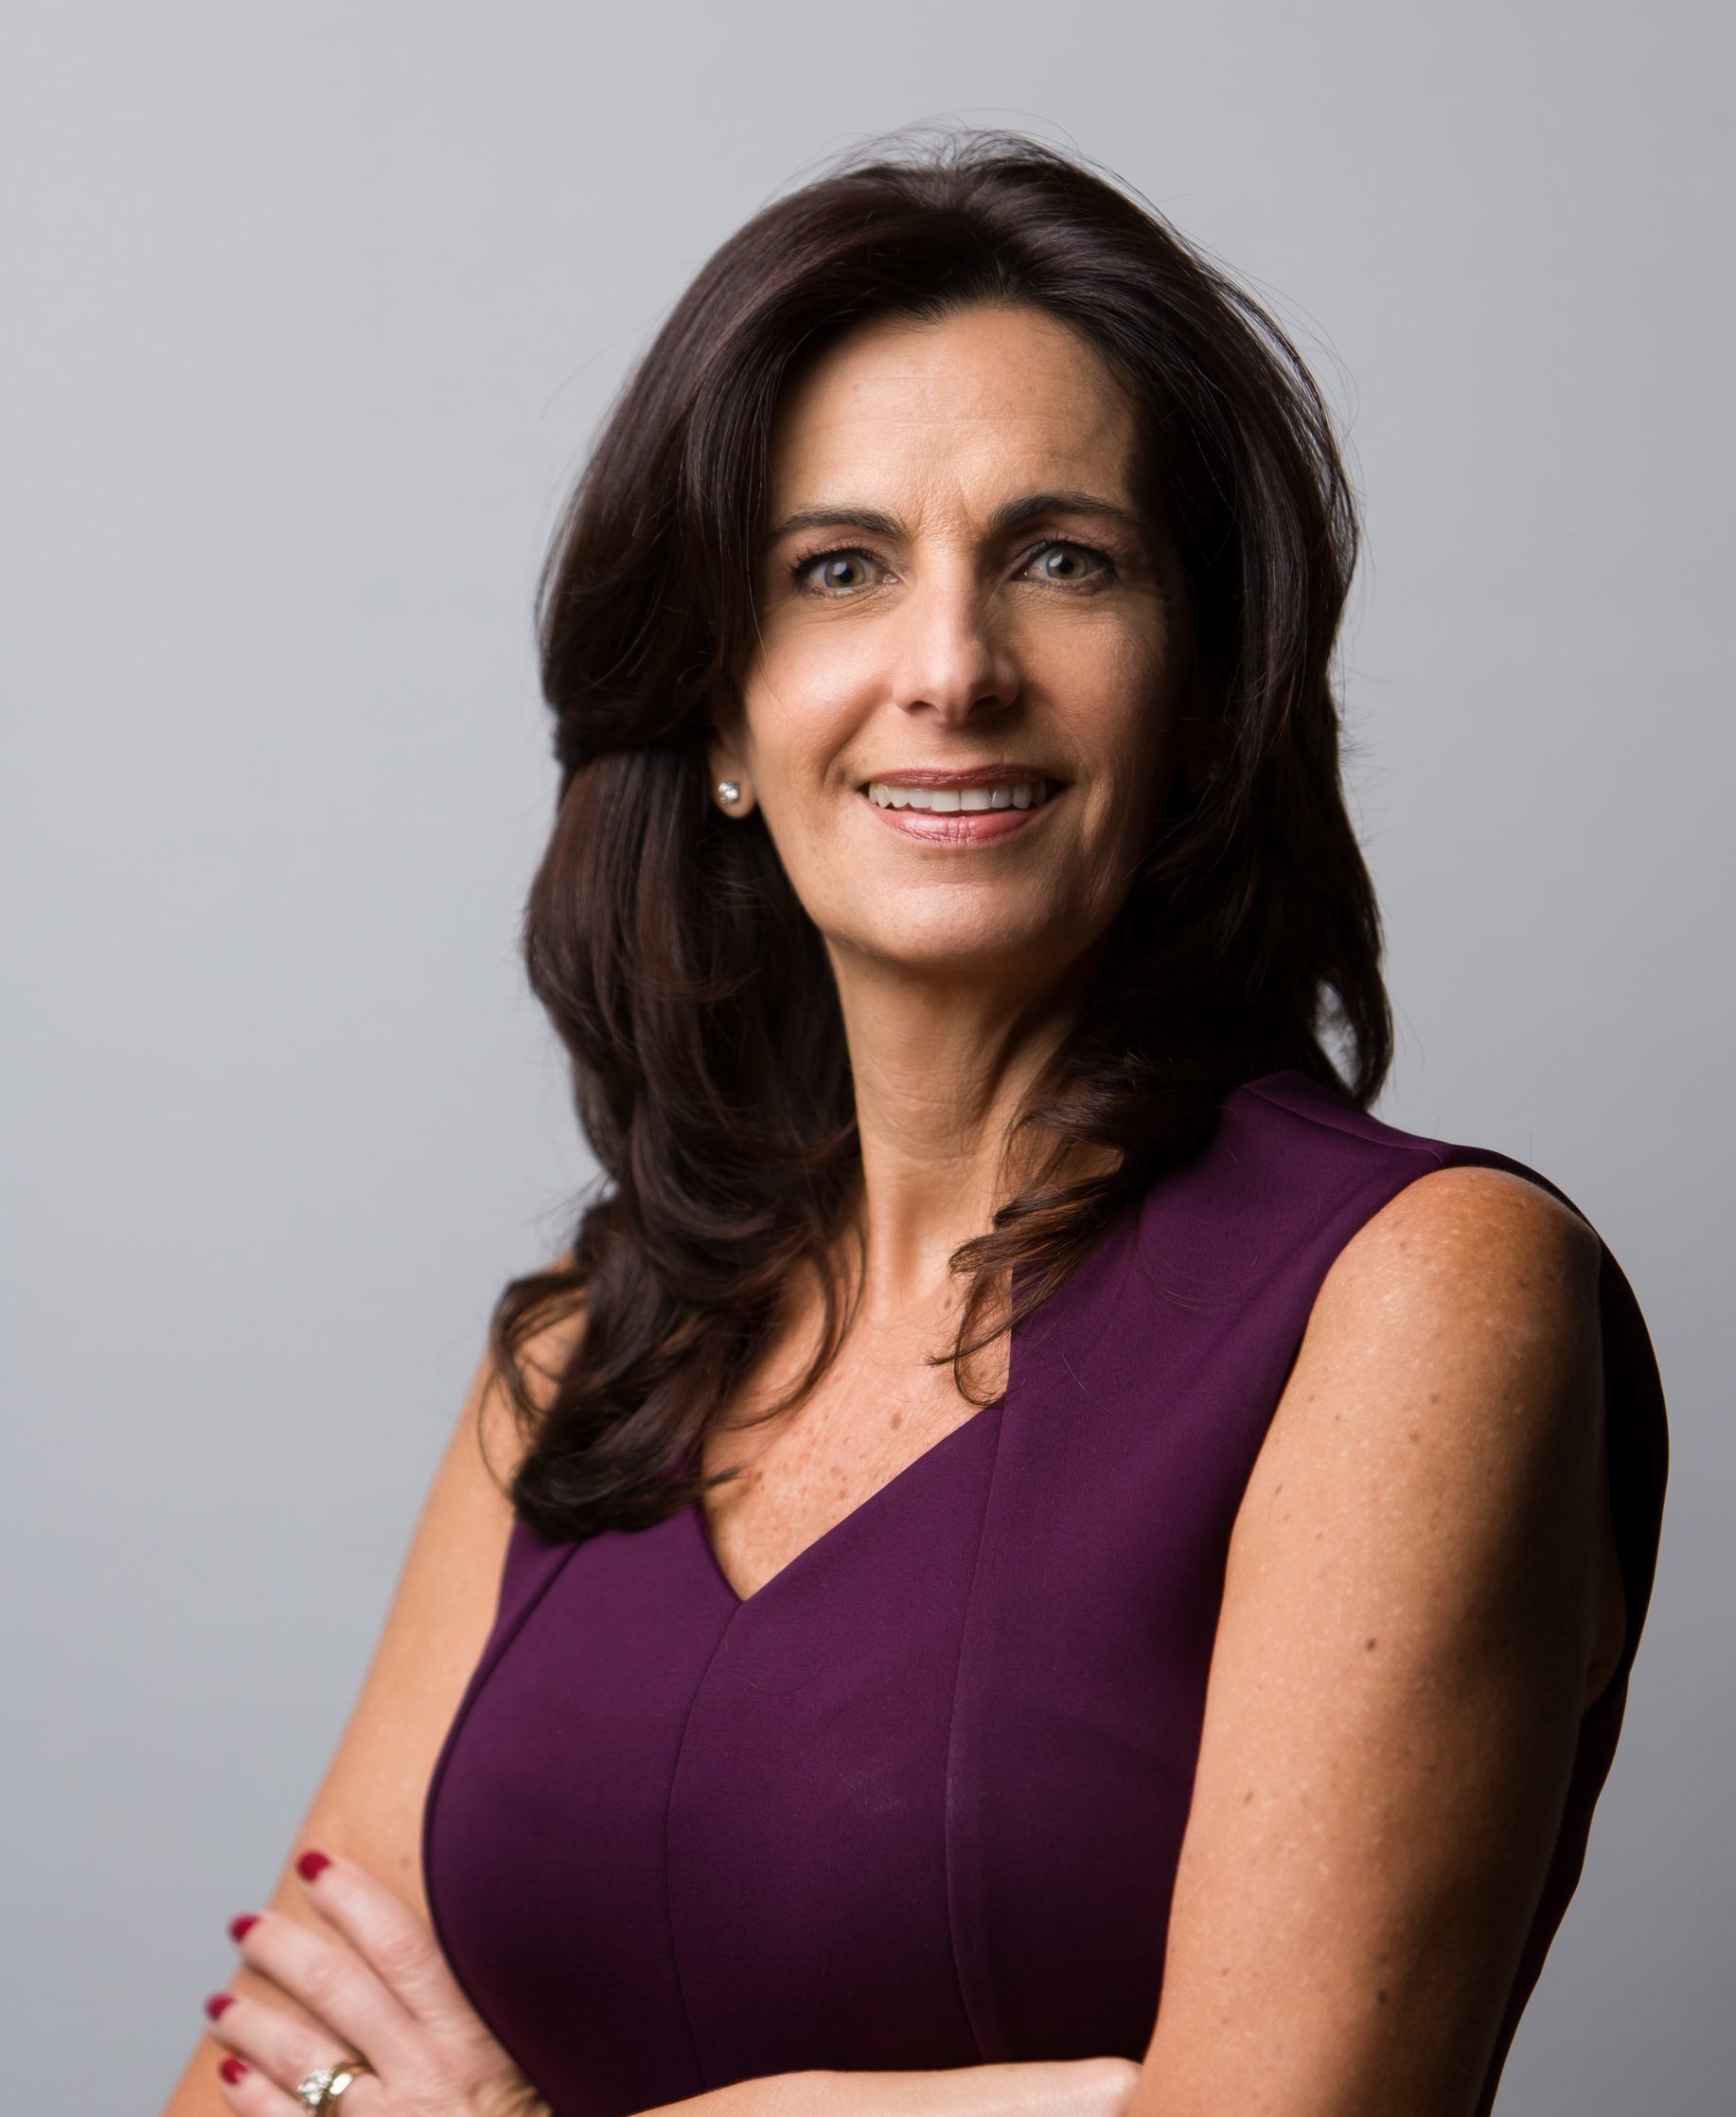
Lidia Longa is a partner with Gerson Preston in the tax and accounting department. With more than 20 years of experience in the public accounting profession, Lidia has practiced in areas of income, estate, trust and corporate tax planning and compliance for domestic and international clients. She specializes in working with high-net worth individuals and owners of closely held businesses.
One day, the work will end, but the planning for that day begins far earlier. We asked Longa about the features of, and differences between, popular retirement accounts.
What’s the sweet spot for employers to make the 401(k) match stand out?
Most employers match 50 cents on the dollar up to 3 to 6% of an employee’s salary. Assuming your salary is $100,000 and if you contribute $20,500 (the maximum amount in 2022), then your employer will match 3%, or $3,000. For many employees this is free money, and they should take advantage of it, assuming they contribute to their 401(k).
Can the contribution ever be put in a cash account, or does the employee always have to choose a fund?
Contributions to a 401(k) plan can be invested in stock or bonds and even a cash account. The decision is a personal decision based on the employee’s comfort level. You should look into the manner the fund is set up, and do not assume if you do not make a decision the contributions will be left in cash, the plan may be setup to be invested in a default fund.
Can you outline the basic differences between an IRA, SEP and Roth IRA?
An IRA is an individual retirement account, assuming you have earned income the maximum contribution is $6,000—or $7,000 if you are 50 years old and over. If you or your spouse have a 401(k), your contributions may not be fully deductible. A SEP is an individual retirement account that an employer or a self-employed individual can establish. Both the employer and the employee can contribute; the employer may deduct their contribution. The employee contribution limit is $20,500 in 2022 and the employer may contribute up to 3%. A SEP plan for a self-employed individual may contribute up to 25% of their earnings up to $61,000 for 2022. A Roth is also an individual retirement account using post-tax dollars. You do not receive a deduction for the contributions, made but the plan allows qualified withdrawals on a tax-free basis.
On SEP IRAs, can you discuss the contribution maximum and also things to beware of if you contribute too much?
The SEP IRA plan can allow up to 25% of your net earnings from self-employment up to $61,000 for 2022. Once you finalize your income and you find you have overcontributed to your SEP IRA, you may distribute (refund) the excess amount. The plan will issue you a Form 1099-R reporting the distribution (overfunded amount), but it will not be marked as taxable. Excess contributions are included in the employee’s gross income if you do not take a distribution and you will be subject to penalty of a minimum of 10% excise tax. You may be able to work with the plan administrator to apply the overfunded amount to the following year’s contributions. Either option should be discussed with you plan administrator and resolved before you file your income tax return including extension.
So many people have launched personal businesses during the pandemic. What’s the best type of plan for an independent contractor? Or things to consider?
An independent contractor is considered a self-employed individual and has many options for retirement. The contractor can have an IRA, a Solo 401(k), a SEP IRA, a Simple IRA or a Defined benefit plan. The most complex plan is the defined benefit plan, but each plan has its pros and cons. There is no best type of plan for an independent contractor; it really is a personal decision based on the facts and circumstances of each person. You may have an I.C. who is in their 50s, is going to make a great deal of money and wants to contribute as much as possible to their retirement. In this case, the I.C. can contribute the maximum amount as they do not need the cash (approximately $245,000). In the other extreme you may have someone just starting out who may not have the cashflow to contribute the maximum amount so they may prefer a Solo 401(k). Retirement planning is very personal and should be discussed with your tax advisor.
Several years ago, trading/investment companies stopped charging per trade (it was around $5 per). One eliminated fees, then the others followed suit. How did this impact the companies’ revenue?
Competition created this change of zero fees but the houses found other ways to change their revenue scheme. Many companies now charge a management fee and others earn interest on client funds that they hold. Other brokerage houses have found creative ways to make up the shortfall of lost commissions.
CNBC’s Jim Cramer advises putting $10k in an index fund for a child or young adult, because if the market performs in the next 40 years like it has in the last 40 years, that $10k will be worth more than $400k. Is that sound advice?
I agree with this advice. I made a similar investment for each of my children to help finance their college. As with any investment, there is no guarantee, but based on past performance, in the long term, the investment does generally increase in value.
What is the most misunderstood thing about retirement accounts?
In my opinion, people in general do not understand the need for retirement accounts. You need to take care of yourself as we don’t know if Social Security will be funded when it is our turn to retire. By contributing over the years and taking advantage of the employer’s match this will create a long-term savings for those retirement years.
Without mentioning names, can you tell an anecdote about how you guided a client with regard to retirement accounts?
We have a client who was going to receive a substantial amount of income prior to retirement and did not need the cash in the immediate future. We were able to front load a defined benefit plan over three years and she was able to deduct the contributions and investment them in her retirement account. After she retired a few years later, we took advantage of her lower income and rolled over her previous employer’s 401(k) into an IRA. We then rolled the IRA into a Roth IRA to take advantage of her lower tax rate. This Roth is now growing tax-free. With proper planning, she was able to save thousands of dollars over the course of a few years.